Online checkout has spent years becoming shorter. Card details moved into digital wallets, one-click purchasing removed repeated forms, and tokenisation allowed merchants to process returning customers without storing the original card number. The next change could be more fundamental because the person buying something may no longer be the party directly operating the checkout.
AI agents are beginning to move beyond recommending products and towards completing transactions on a user’s behalf. A shopper might ask an assistant to find a flight below a certain price, reorder household essentials when supplies run low or purchase a specific product once it becomes available. If the agent is authorised to act, the final payment could happen without the customer manually opening the merchant’s checkout page.
That sounds like a small automation step, but payments are built around knowing who authorised a transaction and under what conditions. Once software begins acting for a consumer, the industry needs a reliable way to distinguish a legitimate delegated purchase from an automated transaction that should be blocked.
Agentic Commerce Is More Than AI-Powered Shopping
AI has already become part of online shopping through recommendation engines, search assistants and customer-service chatbots. Those systems help people decide what to buy, but the customer generally remains responsible for completing the transaction. Agentic commerce extends the process by allowing software to take actions after the decision criteria have been established.
A user could tell an agent to buy train tickets only if the total price stays below a fixed amount. Another instruction might permit a grocery agent to reorder a familiar basket every week but prohibit substitutions above a certain price. The agent would then search, compare options and potentially initiate payment while remaining inside the boundaries defined by the customer.
The difference is important because a recommendation does not move money. A purchasing agent does. That means payment networks cannot simply treat every AI-initiated transaction as ordinary card-not-present ecommerce. They need mechanisms that can communicate that the agent has permission to act, identify the account behind it and show whether the purchase falls within the authority originally granted.
Payments Need to Know Who Is Acting
Traditional ecommerce has several familiar participants. There is a consumer, a merchant, an acquiring bank, an issuer and usually a card network or another payment rail connecting them. Authentication and fraud systems evaluate signals generated during the transaction to determine whether it should proceed.
An AI agent introduces another participant into that chain.
| Payment question | Traditional checkout | Agentic checkout |
|---|---|---|
| Who selects the product? | Consumer | Consumer or AI agent |
| Who initiates checkout? | Consumer | AI agent may initiate it |
| Who provides payment credentials? | Consumer or stored wallet | Tokenised credential available to agent |
| Who sets purchase limits? | Usually consumer at checkout | Consumer may define them in advance |
| Who evaluates the transaction? | Merchant, network and issuer | Same parties, with additional agent signals |
| Who remains financially responsible? | Consumer/account holder | Still requires clear rules and consent |
The challenge is not to give an AI model unrestricted access to a card. A workable system needs the opposite: narrowly defined credentials and permissions that allow the agent to complete approved tasks without exposing the underlying account unnecessarily.
This is one reason tokenisation is likely to be central to agentic payments. Instead of giving an AI system a reusable card number, a payment provider can potentially issue credentials associated with a particular user, agent or transaction context. Those credentials can then carry controls that make them considerably less useful if stolen or used outside the authorised purpose.
Consent Has to Become Machine-Readable
Human checkout contains several moments where consent is relatively obvious. A shopper adds an item to the basket, reviews the total and presses a button to place the order. Even when the card is already stored, there is usually a visible final action.
Agentic commerce complicates that sequence because permission may have been given hours, days or even weeks before the actual purchase. The user might say, “Buy these headphones if they fall below $150,” and then stop interacting with the process entirely. When the price eventually changes, the agent needs to know whether the original instruction still authorises the transaction.
That creates demand for much more precise permissions. Instead of a simple yes-or-no payment approval, an agent may need rules covering:
- a maximum transaction amount;
- approved merchants or product categories;
- how long the authorisation remains valid;
- whether recurring purchases are allowed;
- whether substitutions require confirmation;
- and when the agent must return to the user for approval.
These rules turn consent into something software can evaluate before money moves. They also give issuers and payment networks additional context when deciding whether an automated transaction matches the customer’s expected behaviour.
Checkout Could Become Invisible Without Disappearing
The phrase “invisible checkout” has been used for years, but agentic commerce could make it considerably more literal. If an AI assistant handles discovery, comparison and payment, a customer may never visit the conventional checkout interface at all.
For merchants, that changes what needs to be optimised. Product pages have traditionally been designed for humans who compare images, descriptions, reviews and prices before clicking a purchase button. AI agents need structured information they can interpret reliably: availability, specifications, delivery terms, refund policies and machine-readable pricing.
Payment acceptance also becomes part of that machine-to-machine interaction. The merchant needs to recognise an authorised agent, understand the payment credential it presents and return enough information for the agent to explain what happened to the customer.
The checkout page itself does not necessarily disappear. People will continue to shop manually, particularly for expensive, emotional or complicated purchases. But for predictable transactions, the payment experience may increasingly happen behind an assistant rather than inside a merchant’s visible funnel.
Fraud Detection Faces an Unusual Problem
Payments companies have spent years identifying automated behaviour because bots are frequently associated with card testing, account takeover and other forms of fraud. Agentic commerce introduces a strange reversal: some automated purchasing behaviour will now be legitimate. Blocking every non-human transaction would therefore defeat the purpose of authorised agents. Allowing every automated transaction would create an obvious security problem. Payment systems need to tell the difference.
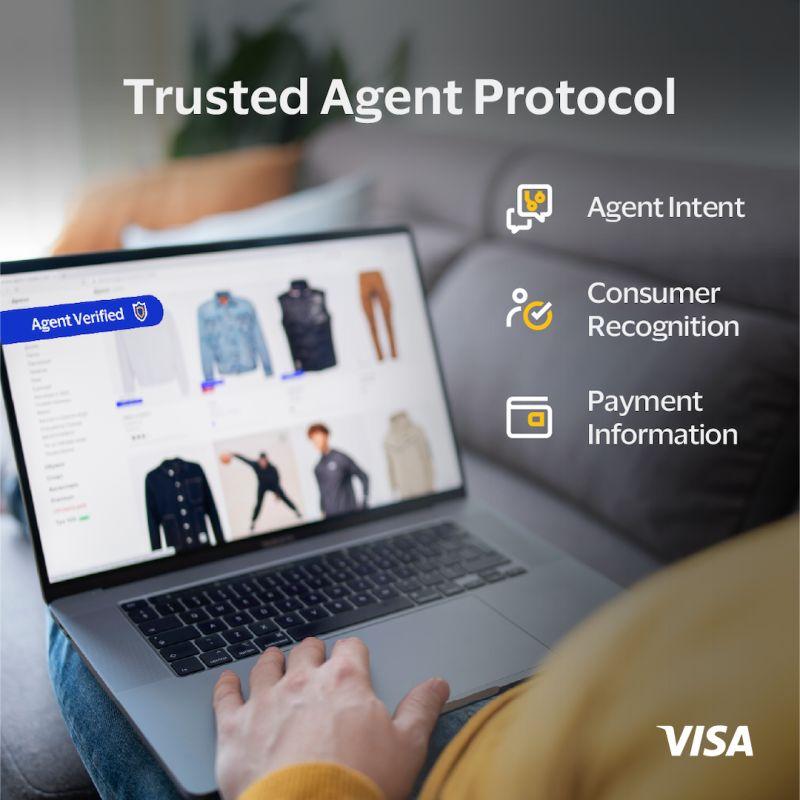
Agent identity could become an important signal. A merchant or issuer may need to know which agent initiated the purchase, which consumer authorised it and whether its behaviour matches the permission attached to the payment credential. Device information and behavioural signals will still matter, but they may be interpreted differently when nobody is expected to be physically typing or clicking.
This could also change fraud models. A transaction completed in milliseconds is suspicious when the system expects a human checkout session, but perfectly normal when a verified purchasing agent is operating through an API. Context becomes more important than the behaviour alone.
Refunds and Disputes Become More Complicated
Making a successful payment is only one part of commerce. Real transactions are returned, cancelled, disputed and occasionally misunderstood. Those processes become particularly interesting when an AI agent has acted between the customer and merchant.
Suppose an agent buys the correct product but chooses a delivery option the user did not expect. The payment itself may be authorised, yet the customer could still argue that the agent acted outside the intended instruction. Similar questions arise when a price changes between selection and purchase or when an agent chooses an alternative product because the preferred item is unavailable.
Clear transaction records will therefore be essential. A future receipt may need to show more than the merchant, amount and timestamp. It could include which agent acted, what authority it had and which conditions were used when making the decision.
This audit trail would help consumers understand automated purchases and could also become important during disputes. If a payment provider can demonstrate that an agent stayed within a clearly defined mandate, responsibility becomes easier to establish than when the original instruction exists only as an ambiguous conversation.
Banks May Need an Agent Control Centre
If agentic payments become common, consumers will need somewhere to manage them. The banking app is an obvious candidate. Instead of seeing only cards and recurring subscriptions, users could eventually see a list of AI agents authorised to spend from an account. Each agent might have its own limits, merchant permissions and expiration date. Access could be paused or revoked without cancelling the underlying card.
That would make agent permissions resemble a combination of card controls, subscription management and connected-app access. A customer could allow a travel agent to spend up to a certain amount for one week while giving a household assistant a smaller recurring allowance.
The best implementations will probably make these relationships visible. Agentic commerce becomes much harder to trust if consumers cannot easily answer a basic question: which software currently has permission to spend my money?
The Payment Button Is Becoming a Permission System
Agentic commerce is sometimes presented as a story about AI becoming good enough to shop. From a payments perspective, the more important development is the infrastructure being built around that ability. Networks and financial institutions need to establish how an agent proves that it is legitimate, how payment credentials are protected, how spending authority is restricted and what happens when a transaction goes wrong. Merchants, meanwhile, need to recognise trusted agents without creating a new route for fraud.
None of this requires consumers to hand complete financial control to an AI assistant. In fact, the technology is more likely to succeed if it does the opposite: giving people granular ways to specify exactly what an agent can and cannot do.
The familiar checkout button represented a simple moment of consent. Agentic payments turn that moment into a set of permissions that may persist across time, merchants and transactions. If that model becomes mainstream, the biggest change in digital payments will not be that AI can buy things. It will be that payment systems learn how to understand when software has genuinely been authorised to act for a human.
