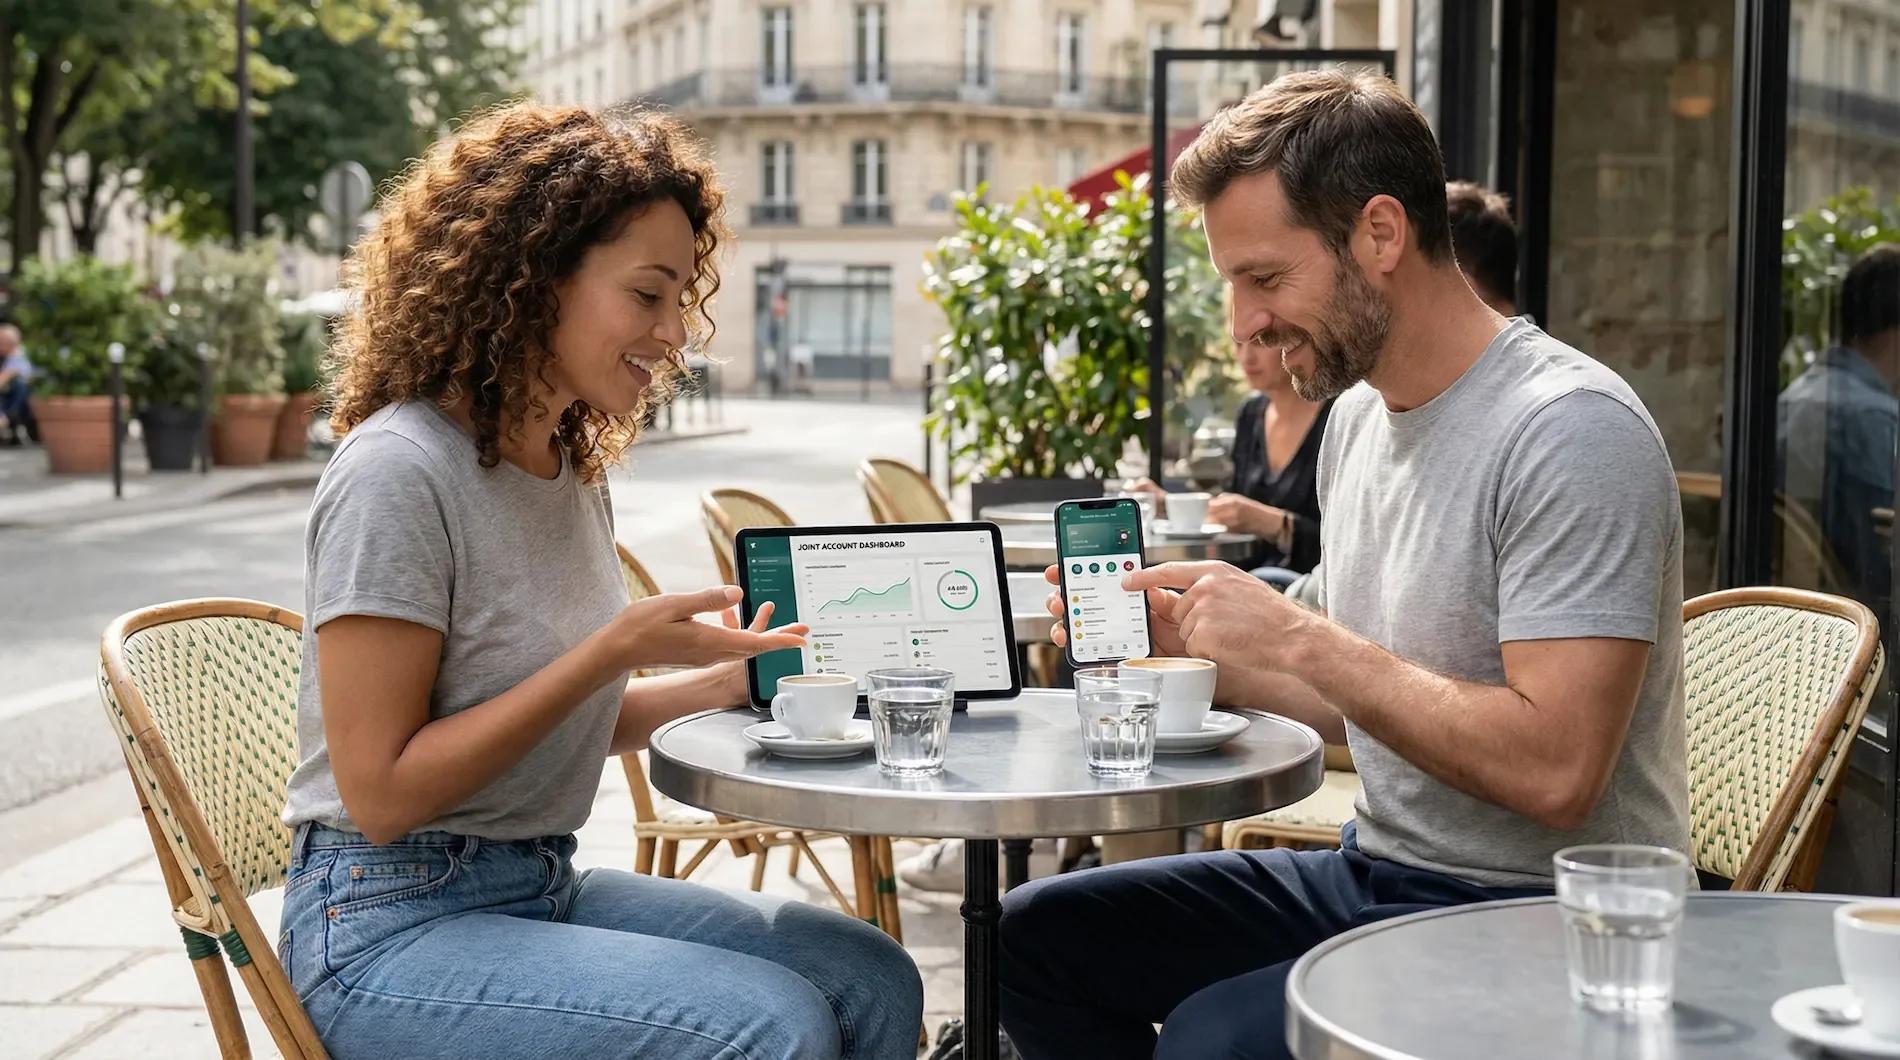
Digital banking was originally designed around the individual. One person logged in, checked one balance, moved money between accounts and managed personal spending. That model still works, but it does not always match how people actually handle money. Couples share rent, families save for holidays, roommates divide household expenses and parents often want to give younger family members limited financial access without opening everything up.
This is helping push shared financial spaces into mainstream banking apps. Instead of forcing users to choose between completely separate finances and a traditional joint account, newer tools can create a middle ground where selected budgets, goals or balances are managed together while personal money remains private.
Joint accounts already support some of this behaviour. Revolut, for example, allows two users to manage a joint account with recurring contributions and dedicated budgeting pockets, while N26 supports joint accounts that can be used for shared bills, transfers and spending insights.
Shared money does not always mean merged money
Household finances have become more flexible because many people do not use a single financial structure for everything. A couple may share housing expenses but keep individual salaries separate. Parents might want one budget for groceries and another for family travel while still maintaining completely private accounts. Roommates may only need a shared pool for utilities.
Shared financial spaces fit these arrangements better than an all-or-nothing joint account. They give users a place to coordinate specific parts of their finances without requiring every transaction to become visible to everyone involved.
That distinction is increasingly reflected in finance products aimed at couples and families. Current family budgeting platforms are emphasizing separate logins, shared goals, role-based permissions and selective visibility rather than assuming every member should see every account.
What a shared financial space can include
The exact structure differs between banking and budgeting platforms, but the underlying idea is similar: several people can contribute to or monitor a defined financial area.
Common features include:
- Shared household spending balances
- Joint savings goals
- Automatic recurring contributions
- Shared bill tracking
- Separate permissions for different users
- Real-time spending updates
- Individual and household budgets in the same app
- Privacy controls for personal transactions
This creates a much more flexible financial setup. Someone can contribute a fixed amount toward household expenses each month without exposing the rest of their spending history, while another household may choose complete transparency.
Traditional joint accounts vs shared financial spaces
| Feature | Traditional joint account | Shared financial space |
|---|---|---|
| Shared balance | Yes | Usually |
| Separate personal finances | Possible, but outside the account | Built into the structure |
| Selective visibility | Limited | Often available |
| Shared savings goals | Sometimes | Common |
| Role-based permissions | Rare | Increasingly common |
| Multiple shared budgets | Limited | Often supported |
| Best suited for | Fully shared expenses | Flexible household finances |
The difference is important because many households do not manage money in only one way. They may have personal accounts, shared subscriptions, individual investments and several common savings goals at the same time.
Banking apps are becoming coordination tools
The larger change is not simply the addition of another account type. Banking apps are increasingly moving toward financial coordination. A shared household space can show how much has been contributed toward rent, whether an upcoming bill is covered and how close the family is to a savings target. Instead of discussing these figures separately through spreadsheets or messaging apps, users can see the same information inside their banking environment.
Shared budgeting services are already moving in this direction. Some allow households to view joint spending in real time while maintaining different privacy levels for individual accounts, budgets and goals.
This approach can also reduce the amount of manual administration involved in household finances. Automatic contributions, recurring bills and shared categories mean users do not have to repeatedly calculate who owes what.
Privacy is becoming just as important as transparency
Shared finances often create a difficult balance. Too little visibility can make household budgeting confusing, while complete visibility may feel unnecessarily intrusive.
The next generation of shared banking features is therefore likely to focus heavily on permissions. One user may be allowed to see a shared grocery budget but not another person’s personal purchases. Parents could potentially give teenagers access to a spending allowance while retaining broader control over the account.
This type of selective sharing already appears in family finance products, where personal, shared and co-managed categories can coexist inside the same system. The result is a more realistic model of household finance. Financial cooperation no longer has to mean giving every participant identical access to everything.
Why banks have an incentive to build these features
Shared spaces also make sense from the bank’s perspective. A customer who uses an app only to check a balance may interact with it briefly. A household using the same platform for rent, groceries, savings targets and recurring bills has many more reasons to return.
Shared features can also strengthen the relationship between a financial institution and an entire household rather than only one account holder. Once several recurring financial activities are organised inside one banking ecosystem, switching services becomes more complicated. For banks and fintech companies, that makes shared money management both a useful customer feature and a potentially powerful retention tool.
The next step may be configurable household banking
The traditional distinction between an individual account and a joint account is unlikely to disappear, but it may become less important as banking apps become more configurable.
Instead of opening one account for every financial purpose, users could increasingly create different spaces inside one financial environment: one for personal spending, another for household costs, another for a holiday and another for long-term family savings.
Each space could have its own participants, permissions, cards, contribution rules and spending limits. That would make banking infrastructure much closer to the way people already organise money mentally.
A more flexible model for everyday finance
Shared financial spaces represent a relatively simple product idea, but they solve a complicated problem. Modern households often combine shared responsibilities with individual financial independence, and traditional account structures do not always handle that combination elegantly.
Banking apps that allow users to decide exactly what is shared, who can access it and how money moves between personal and collective budgets can make household finance considerably easier to manage. As digital banking continues evolving, the most useful innovation may not be another standalone financial product, but a better way for several people to manage money together from the same app.
